TL;DR: Filing a roof insurance claim in Texas has real deadlines, legal protections, and common pitfalls that can cost you thousands if you miss them. This guide walks Corpus Christi-area homeowners — from Alice to Aransas Pass to Beeville — through every step, from documenting storm damage to collecting your final payment. Know what to do, what to avoid, and what Texas law requires your insurer to do.
A Gulf storm rolls through the Coastal Bend. You walk outside the next morning and spot shingles in the yard, dents along the gutters, or water staining on the ceiling inside. The roof took a hit — now what?
Filing a roof insurance claim in Texas sounds straightforward. In practice, it has moving parts, strict deadlines, and more than a few traps for homeowners who haven’t been through it before. This guide lays out the full process in plain English, written specifically for homeowners in Corpus Christi, Alice, Aransas Pass, Banquete, and Beeville — communities that face a combination of hurricane-force wind, coastal salt air, hail, and intense Gulf humidity that few other markets deal with.
Why This Process Matters More on the Texas Coast
Corpus Christi carries an extreme Wind Factor™ risk based on the projected likelihood and speed of hurricane, tornado, or severe storm winds — and is most at risk from hurricanes. During Hurricane Harvey alone, wind damage stripped thousands of roofs to the decking in Corpus Christi and the Coastal Bend.
Texas homeowners file roof insurance claims at rates that consistently rank among the highest in the United States, driven by the state’s exposure to hail, tropical storms, and severe convective wind events. Insurers know this territory well — and so should you before you pick up the phone.
Before You File: Two Things to Understand
ACV vs. RCV Coverage
Your policy type determines how much money you actually receive. Replacement Cost Value (RCV) policies pay for a new roof at today’s prices. Actual Cash Value (ACV) policies deduct for depreciation based on the age and condition of your existing roof, meaning an older roof might get you far less than the actual repair cost.
As your roof ages, some insurers will automatically switch to ACV coverage at renewal. Check your declarations page before a storm hits — not after.
Your Wind-Hail Deductible
Most Texas carriers now split wind-hail from the all-perils deductible. It’s often 1% to 5% of dwelling coverage and applies specifically to storm claims. In coastal Texas, most policies include percentage-based wind and hail deductibles that can represent a meaningful out-of-pocket cost even on an approved claim. On a home insured for $300,000, a 2% wind-hail deductible means $6,000 comes out of your pocket first.
What You Need Before You Start
- Your homeowners insurance policy (declarations page and full policy document)
- The exact date and time of the storm event
- A phone or camera with video capability for documentation
- Any prior inspection or maintenance records for your roof
- A notepad or app to log every call, email, and contact name with timestamps
- Receipts for any emergency materials (tarps, etc.) you purchase immediately after the storm
Step-by-Step: How to File a Roof Insurance Claim in Texas
-
Document the damage before touching anything.
Take photos and videos from multiple angles — wide shots of the full roof, close-ups of each damaged area. Inside the house, photograph any water stains, mold, or drywall damage. Also photograph gutters, siding, downspouts, AC units, and any debris. Write down the exact date and time of the storm. Texas carriers can deny claims filed against the wrong storm date, so precision matters.
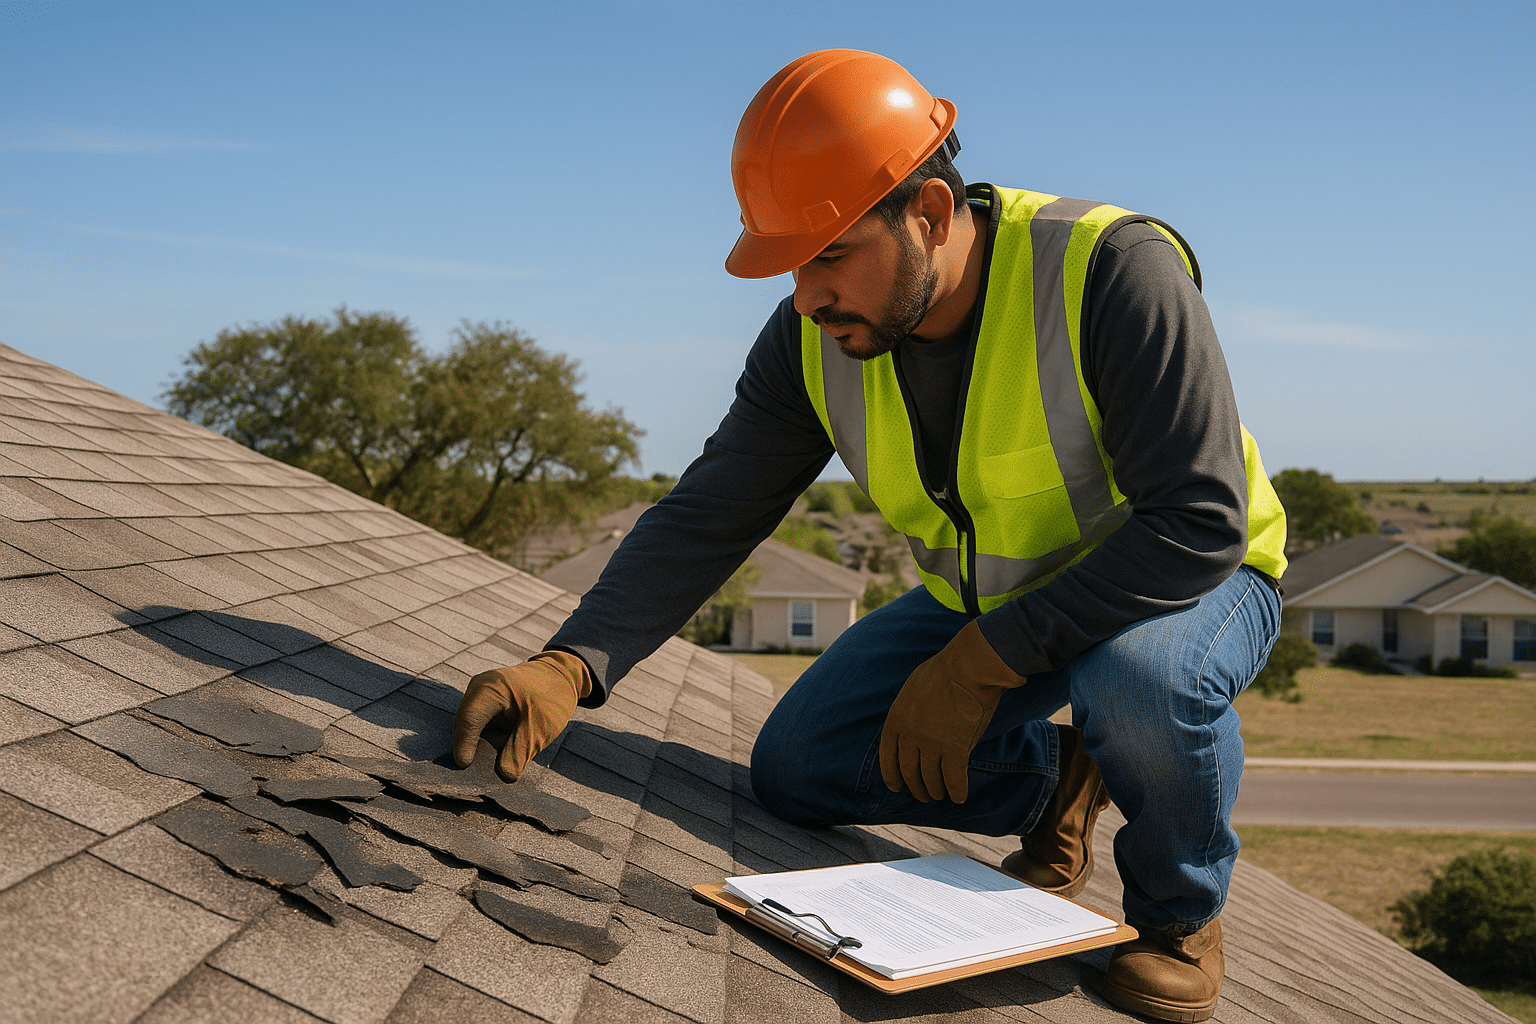
A thorough assessment covers the roof, gutters, flashing, vents, skylights, and other roofing components. The attic and interior of the home should also be checked for signs of water intrusion. Photographs, measurements, and notes are collected to help evaluate the claim.
-
Make emergency temporary repairs.
Homeowners should take reasonable steps to prevent additional damage, such as placing a tarp over exposed areas or moving belongings away from leaks. Keep every receipt — most policies reimburse reasonable emergency mitigation costs. In the Corpus Christi area, South Texas humidity enables mold growth within 24–48 hours of sustained water intrusion, so acting fast is not optional.
-
Get a professional assessment before you call your insurer.
This step surprises most homeowners, but it’s one of the most important. Hire a roofing contractor licensed by the Texas Department of Licensing and Regulation (TDLR) to conduct their own assessment before or immediately after the adjuster visits. Their written findings give you an independent baseline and help ensure the adjuster doesn’t overlook damage.
In Corpus Christi and nearby communities like Aransas Pass and Banquete, the Texas Coastal Bend experiences recurring hail and severe thunderstorm events outside of hurricane season. Hail damage to asphalt shingles — including granule loss, mat core impact, and cracked ridge caps — is often invisible from the ground and requires a professional inspection to document correctly.
Buffalo Roofing & Exteriors offers free estimates across the Corpus Christi area, including Alice, Beeville, and Aransas Pass. If there’s damage worth filing on, we’ll tell you. If there isn’t, we’ll tell you that too — because filing a claim with no payable damage only creates a mark on your loss history. Ask about our professional shingle roof repair services in Corpus Christi if storm damage turns out to be localized to a few sections.
-
Notify your insurance company promptly.
Start by reporting the damage as soon as you discover it. Early reporting gives the insurance company an opportunity to inspect the property while the damage is still fresh and easier to document. Most policies have a reporting requirement — waiting weeks can give the carrier grounds to dispute your claim.
When you call, have your policy number ready, the storm date, and a summary of what you documented. Ask for your claim number and the name of the adjuster assigned to your file. Write it all down.
-
Know your legal rights under Texas law.
Texas gives homeowners strong statutory protections. The Texas Department of Insurance (TDI) governs insurer conduct in the state, and the Texas Insurance Code establishes the procedural rules that apply to all residential property claims.
Specifically, insurers have 15 days to acknowledge a claim and request documents, 15 business days to accept or reject once receiving all information, and 5 business days to pay an accepted claim — all under the Texas Prompt Payment of Claims Act (Chapter 542 of the Texas Insurance Code). Missing deadlines exposes carriers to penalties including 18 percent annual interest plus attorney’s fees.
You can learn more about your rights directly from the Texas Department of Insurance’s roofing and insurance page.
-
Meet the adjuster — and have your contractor there too.
After you submit a claim, an insurance adjuster will be sent to independently assess the damage and determine the cost that the insurance company will pay out for the repairs. Request the adjuster’s visit date and arrange for your roofing contractor to be present at the same time.
Having a licensed contractor on the roof with the adjuster is legal and strongly recommended. Insurers sometimes undercount damaged sections, apply excessive depreciation, or overlook secondary damage such as soffit or flashing issues. A contractor who knows what storm damage looks like on a Coastal Bend roof can make sure nothing is missed in real time.
Important legal note: Texas doesn’t allow a roofer or contractor to act as a public insurance adjuster on insurance claims if they’re also doing the work. Buffalo Roofing & Exteriors documents the damage and is present when the adjuster arrives — but you, the homeowner, are the one who files and manages the claim.
-
Review the settlement offer carefully — don’t rush to accept.
After the adjuster submits their report to your insurance company, you will be given an offer based on the adjuster’s findings. This offer will show how much they are going to pay to fix it. Do not rush through the offer — make sure it covers your estimations and the actual damage.
Compare the insurer’s estimate line by line against your contractor’s written assessment. If the numbers don’t line up, you have the right to negotiate. If the settlement offer doesn’t cover the documented damage, gather additional evidence — photos, contractor estimates, weather reports — and submit a formal dispute.
Also understand how payment works on an RCV policy. On an RCV claim, the carrier doesn’t cut one big check — they cut two. The first check covers the Actual Cash Value (ACV) of your roof in its current depreciated condition. Once the work is completed and documented, you submit a completion certificate and receive the second check — the “recoverable depreciation” — which brings you up to full replacement cost.
-
Select a licensed, local contractor and complete the work.
If the roofing repairs are covered by your homeowners insurance, you will be issued funds to repair the damage, and can then choose the roofing contractor to complete the repairs or replacement. Make sure you select a reputable contractor who is licensed and insured.
One important Texas law every homeowner should know: HB 2102 makes it a misdemeanor for any roofing contractor to pay, waive, or rebate any portion of an insurance deductible. Penalties include up to a $2,000 fine and up to six months in prison — for the contractor and, potentially, for the homeowner who knowingly participates. If anyone offers to “cover your deductible,” walk away.
Buffalo Roofing & Exteriors is licensed and insured, and we serve homeowners across the Corpus Christi metro — including Alice, Aransas Pass, Banquete, and Beeville. We handle asphalt shingle, metal, clay tile, Spanish tile, concrete tile, and flat roof systems including TPO (thermoplastic polyolefin, a single-ply membrane common on commercial and low-slope residential roofs). Ask about our Improvifi financing — from $1,000 to $50,000, $0 down, no credit score impact — if the gap between your settlement and your deductible needs bridging.
-
Collect your final depreciation payment.
Once the work is complete, notify your insurer and submit any required completion documentation — typically a contractor invoice and photos of the finished roof. The insurer then releases the withheld depreciation. Keep copies of everything for your records.
The full process takes 30 to 90 days if nothing gets disputed, and 90 to 180 days if it does. Stay organized and keep a running log of every communication.
If Your Claim Is Denied or Underpaid
Don’t accept a denial as the final word. If the insurer continues to underpay or deny the claim, you have several options: request an appraisal under your policy (most policies include an appraisal clause for disputed amounts), file a complaint with the Texas Department of Insurance, or consult an experienced Texas property damage attorney.
Filing a TDI complaint is free, does not require an attorney, and creates an official record that strengthens your position in any subsequent dispute or litigation. You can reach the TDI Consumer Help Line at tdi.texas.gov/complaints or by calling 1-800-252-3439.
Under Texas law, the statute of limitations to sue an insurance company for a wrongful denial is two years from the date the claim accrues — typically the date of the denial or underpayment. Don’t wait.
Common Mistakes That Cost Corpus Christi Homeowners Money
- Waiting too long to document or report. Storm damage evidence degrades fast in South Texas heat and humidity. Report promptly.
- Going on the roof yourself. It’s dangerous and risks voiding policy provisions. Get a professional up there instead.
- Filing when damage is below your deductible. If the damage is minor and below your deductible, filing creates a claims history without any payment. A free estimate from a contractor first tells you whether it’s worth it.
- Accepting the first offer without comparing it to a contractor estimate. Claims that are poorly documented, filed late, or missing key damage points routinely get underpaid.
- Working with a contractor who offers to waive your deductible. It’s illegal in Texas — for both the contractor and the homeowner.
- Not having a contractor present during the adjuster visit. This is the single most effective way to ensure all damage is captured in the initial scope.
A Note on TWIA for Coastal Bend Homeowners
If you own a home in a designated Gulf Coastal Area — which includes Corpus Christi, Aransas Pass, and surrounding Nueces and San Patricio County communities — you may carry a separate wind policy through the Texas Windstorm Insurance Association (TWIA) in addition to your standard homeowners policy. Corpus Christi homeowners typically carry three separate policies that each apply to roofing damage: private homeowner insurance for hail and fire; TWIA for wind damage in the Gulf Coastal Area; and NFIP flood insurance for storm surge.
Each policy has its own claims process, its own adjuster, and its own deadlines. Make sure you’re filing with the right carrier for the right peril. Buffalo Roofing & Exteriors is experienced with TDI-compliant WPI-8 windstorm certification — the form required by TWIA to certify that a repaired or replaced roof meets Texas windstorm construction standards — and can walk you through what’s needed to keep your coastal coverage intact.
Ready to Get Started? We Can Help.
Buffalo Roofing & Exteriors is a locally owned, BBB-accredited roofing contractor serving Corpus Christi, Alice, Aransas Pass, Banquete, Beeville, and surrounding South Texas communities. We’re licensed, insured, and carry 200+ five-star Google reviews from homeowners who’ve been through this exact process.
We’ll come out, get on the roof, document what we find, and give you a clear, honest picture of whether filing a claim makes sense — all at no charge. Contact us today for your free estimate.
Recommended Reads
- Siding Installation in San Antonio: Best Materials for Texas Heat and UV
- Flat Roof Repair in Corpus Christi, TX
- Professional Shingle Roof Repair in Corpus Christi, TX
Sources
- roofraidersandco.com
- texasroofauthority.com
- fittslawfirm.com
- thejonesboys.com
- tdi.texas.gov
- firststreet.org